DSCR Loans Let Builders Skip Tax Return Requirements
DSCR loans let builders qualify based on property income instead of personal tax returns. This approach simplifies approval for self-employed investors and emphasizes cash flow over paperwork.
Loading...
Showing articles 37 - 48 of 553
DSCR loans let builders qualify based on property income instead of personal tax returns. This approach simplifies approval for self-employed investors and emphasizes cash flow over paperwork.
Updated 2026 building codes establish clear standards for taller mass timber structures, reducing approval times and increasing lender confidence in CLT construction.
A 2-1 buydown temporarily lowers mortgage rates for the first two years. This builder supported option can save buyers up to 40000 dollars while easing the transition to homeownership.
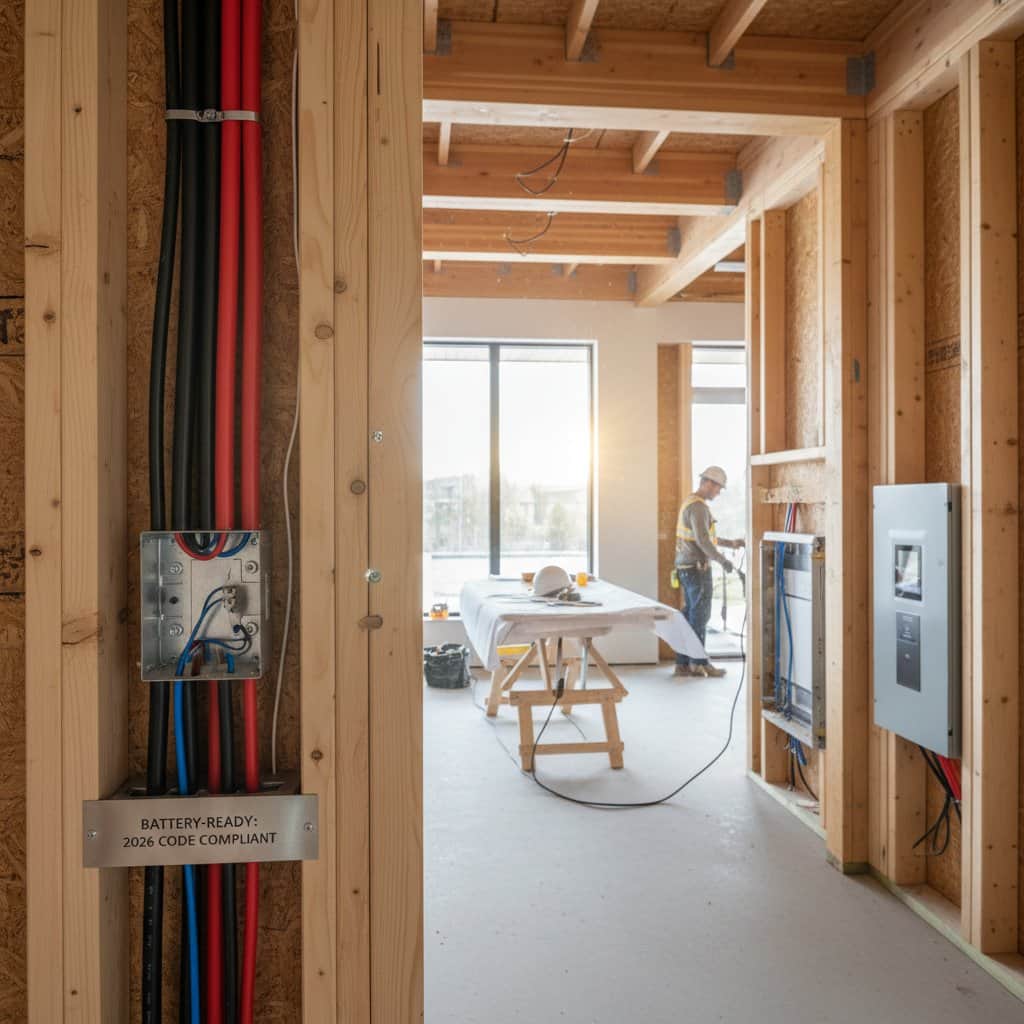
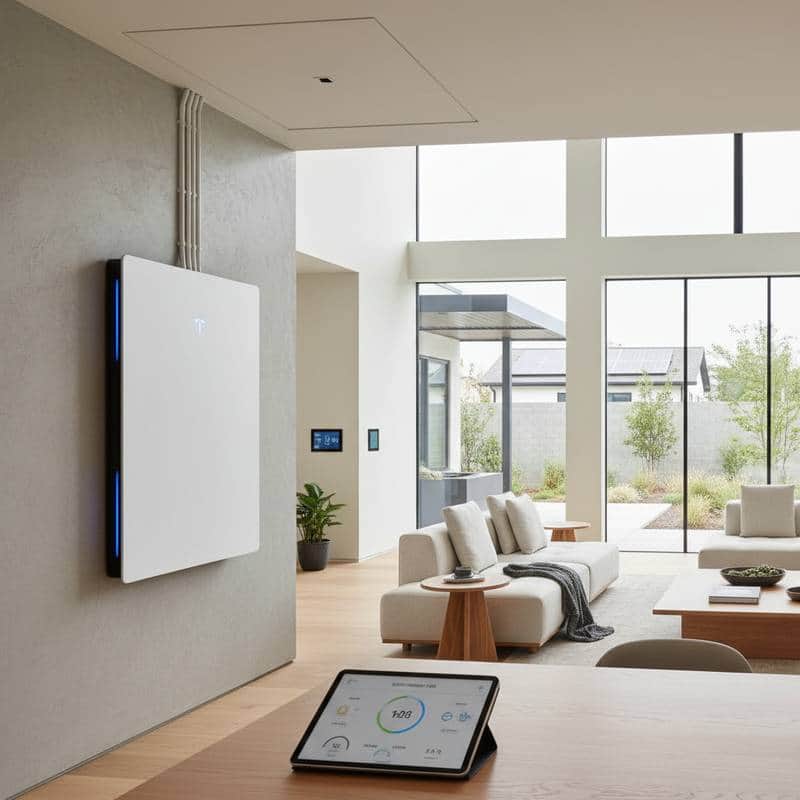
Pre-wiring homes for batteries during construction saves thousands in future retrofits, boosts property value, and ensures compliance with evolving energy codes. It is a small step that makes adding solar storage seamless later.
Builders compete in 2026 through mortgage rate buydowns that lower early payments. Buyers gain from understanding costs, timing, and contract terms before selecting an offer.
Builder rate buydowns lower mortgage rates on new construction homes through builder-funded payments to lenders. This overview covers temporary and permanent structures, qualification considerations, and practical steps to evaluate offers in 2026.
Builders are funding ten home projects without tax returns by using DSCR loans that evaluate property income potential. This approach simplifies qualification, supports phased construction, and rewards strong rental projections with flexible terms.
Mass timber is redefining multi-story home construction with its strength, sustainability, and natural warmth. Using engineered wood panels like CLT, builders achieve faster, cleaner builds and beautiful, carbon-storing structures.
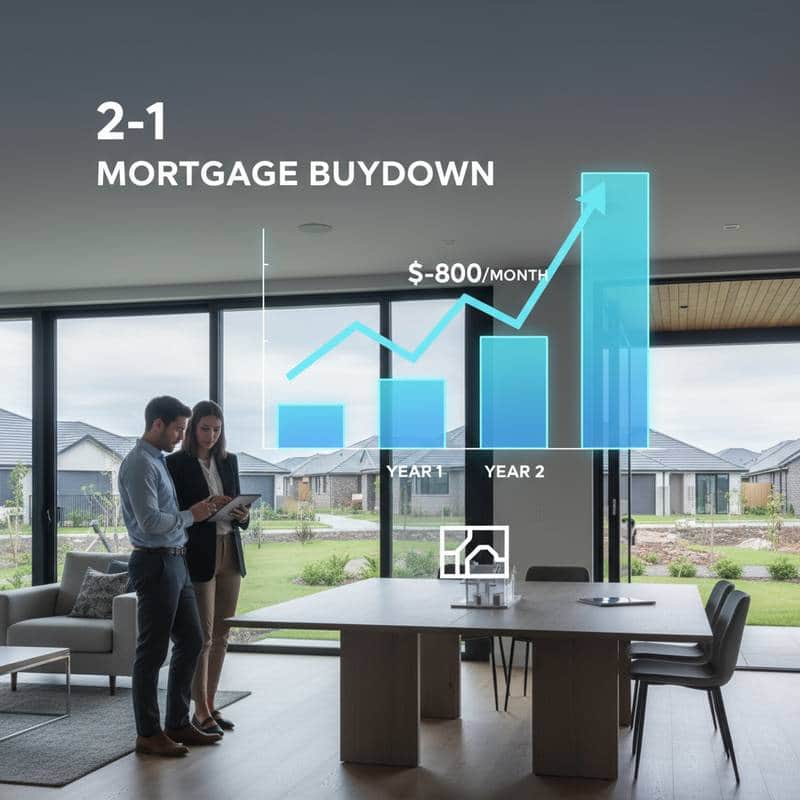
A 2-1 mortgage buydown lowers your interest rate for the first two years, easing early homeownership costs by as much as $40,000. Discover how builders fund this option, how payments adjust over time, and steps to secure long-term financial stability.
Builder paid mortgage buydowns temporarily lower interest rates and ease initial payments for new home buyers. Understand how these incentives function, the reasons builders offer them, and the steps required to avoid future payment surprises.
New 2026 building rules emphasize homes that withstand floods and fires through smarter design, durable materials, and climate-specific planning. From raised foundations to ember-resistant roofs, resilience now blends seamlessly with comfort and style. Thoughtful design choices protect families, reduce long-term costs, and reconnect modern living with the natural environment.
Mass timber high-rises are transforming skylines as code approvals unlock taller wooden structures. Engineered timber offers strength, speed, and carbon benefits compared with steel and concrete.
A construction-to-permanent loan merges construction financing and a mortgage into one streamlined agreement. Borrowers close once, lock terms early, and avoid managing multiple lenders during the build process.
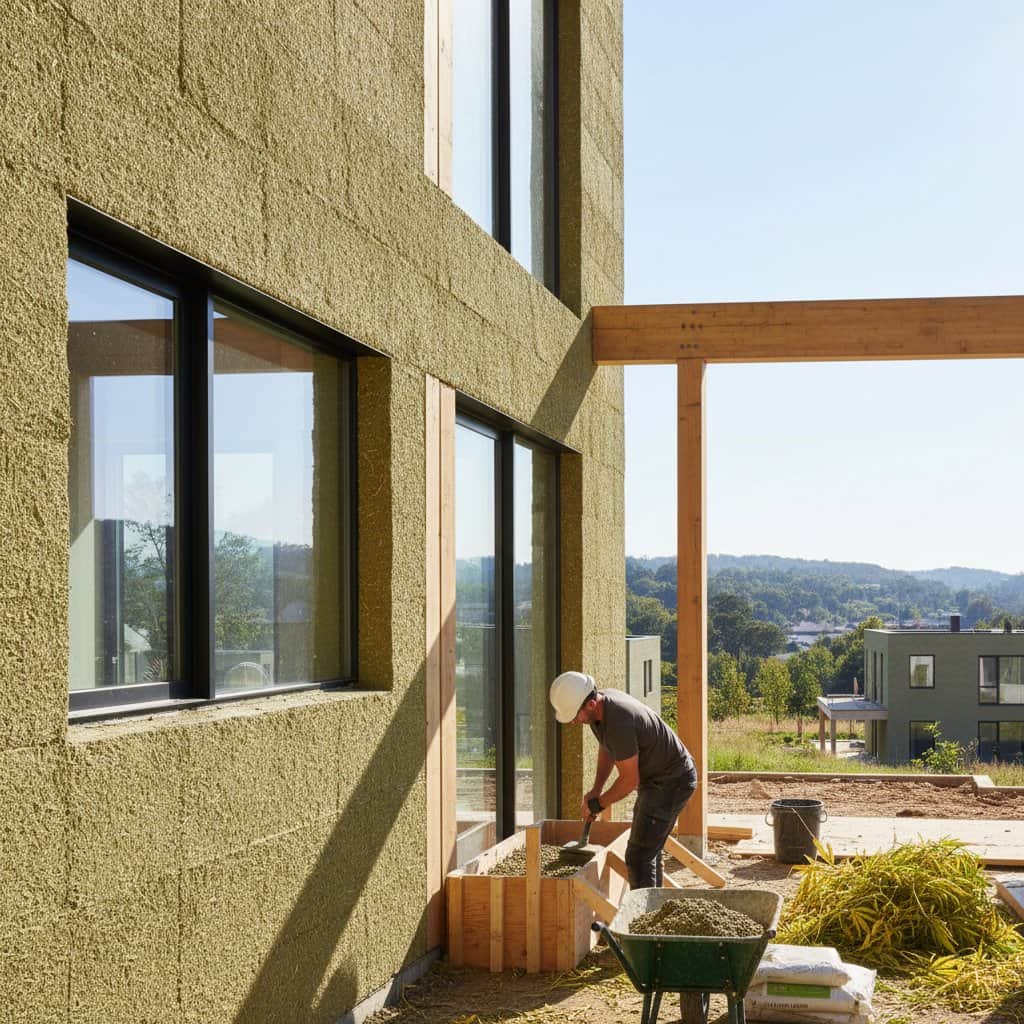
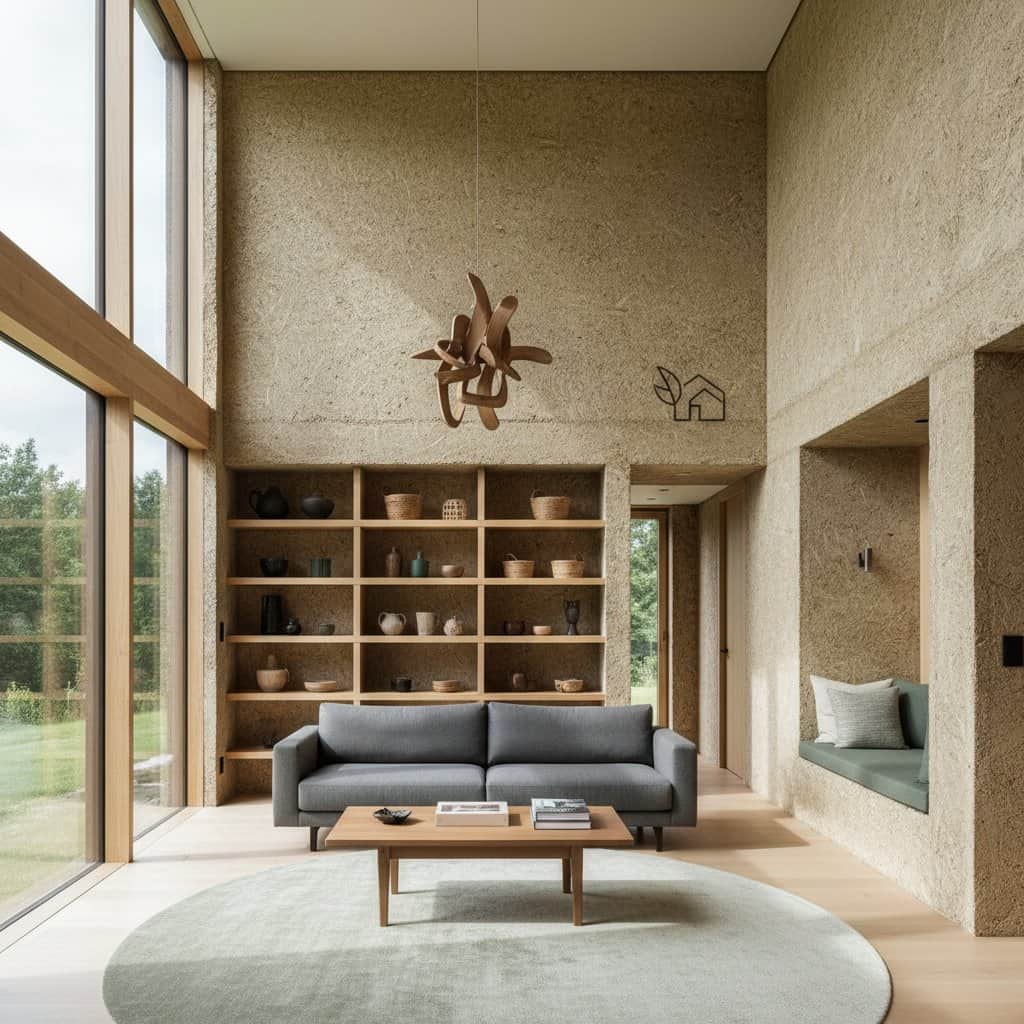
Hempcrete redefines eco-conscious construction through its carbon-negative properties, breathability, and longevity. Composed of hemp hurd, lime, and water, it forms walls that optimize temperature control, combat mold, and elevate indoor environments. With growing adoption, hempcrete positions itself as a cornerstone of green building practices by 2026.
Builder buydowns assist 2026 homebuyers in countering elevated mortgage rates through temporary payment reductions funded by builders. Structures such as 1-0, 2-1, or 3-2-1 buydowns reduce initial costs, improve affordability, and create potential refinancing paths, rendering desirable homes accessible while supporting builder sales in a challenging market.
In 2026, builder mortgage rate buydowns emerge as a leading incentive to improve new home affordability. These arrangements temporarily reduce interest rates, which lowers early payments without altering the home price. Understand the mechanics of these savings, potential considerations, and how they align with your homeownership objectives.
Hempcrete redefines eco-conscious building in 2026 with its blend of hemp, lime, and water forming breathable, carbon-negative walls. These structures provide excellent temperature regulation, fire and mold resistance, and centuries-long durability. Professionals and residents value its comfort, adaptability, and sustainable qualities, positioning it as a cornerstone of resilient, thoughtful design.
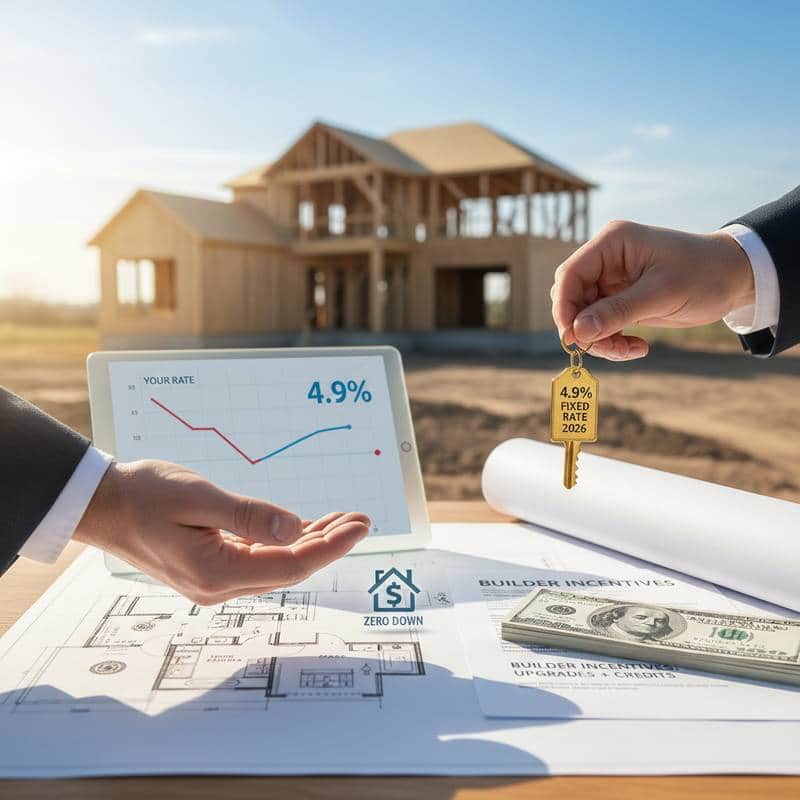
Zero-down builder loans enable homebuyers to commence new construction without an initial down payment while securing a 4.9% interest rate to shield against market fluctuations. Builders enhance these offers with incentives such as upgrades or closing cost assistance, yet buyers must scrutinize rate locks, associated fees, and project timelines to optimize benefits and prevent unexpected expenses.
By 2026, new constructions incorporate battery-ready features for effortless power wall and solar integration. These homes deliver energy autonomy, cost savings, and outage resilience, benefiting builders and residents through sustainable, adaptable designs that transform residences into efficient energy centers.
A 2-1 buydown lowers monthly mortgage payments by up to $800 during the initial years, providing financial relief for new homeowners. This option delivers temporary rate reductions, builder incentives, and opportunities for future refinancing to support long-term stability.
© 2026 Multi HB. All rights reserved.